Blog by Business360.CPA, senior-led accounting and advisory firm in Vancouver | Published November 2026 | Last reviewed November 2026
In Canada, buying equipment tends to make sense when the business can pay for it without straining cash flow and the machine is likely to pay for itself within a few years. Leasing fits better when keeping cash available matters more and the monthly payments still work in a slower month. If you are buying equipment before year-end for the tax deduction, note that capital cost allowance (CCA) generally starts when the equipment is available for use, not when it is ordered or paid for, so let the business case lead and the tax timing follow.
A year-end tax deduction can make a new machine sound attractive. But the first question is not, “How much can we write off?” It is, “Will this machine improve the business without leaving us short of cash?”
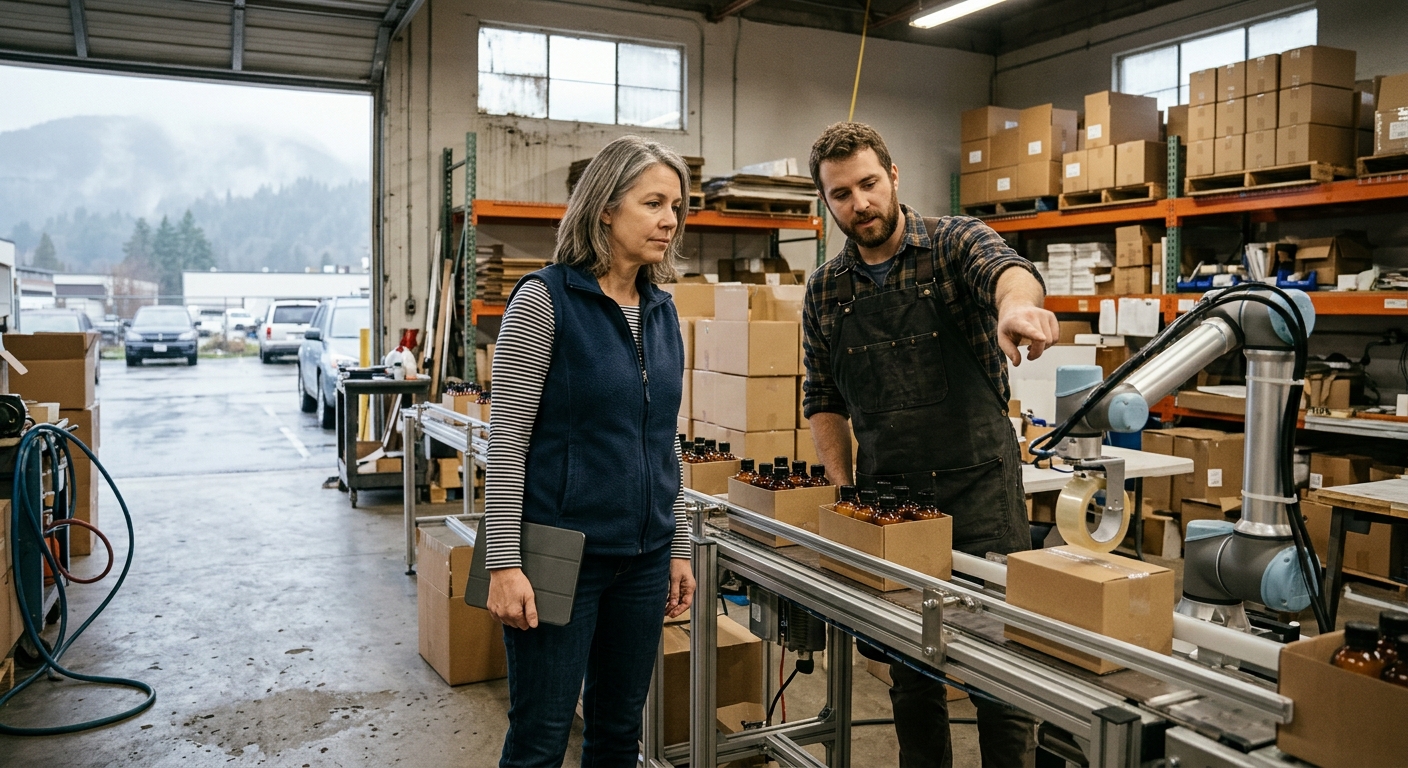
Take a small Lower Mainland manufacturer that fills and packages personal-care products. Orders are growing. Staff are working extra hours to pack boxes, and the owner is considering an $85,000 packaging line with a compact robotic arm. It would label, pack and seal products more quickly. The owner must decide whether to buy it, finance it or lease it.
Lease vs Buy Equipment: Which Fits Your Situation?
Use this as a starting point. The right answer depends on your cash position, plans and the terms you are offered.
| Factor | Buying (cash or loan) tends to fit when… | Leasing tends to fit when… |
| Cash on hand | The purchase still leaves a comfortable cash cushion | Cash needs to stay available for payroll, inventory or growth |
| How long you will use it | The machine will be used for many years | Needs may change or the technology may date quickly |
| Cost focus | Lower total cost over time matters most | Predictable monthly payments matter most |
| Ownership | You want the asset and its resale value | You are comfortable returning it or buying it out at the end |
| Tax treatment | CCA is claimed over time once the asset is available for use | Lease payments are generally deducted as they are incurred |
1. What problem will the machine solve?
Before looking at the price, be clear about the problem. Is the packing line stopping the business from filling orders? Will the new machine cut paid overtime, reduce damaged products or allow the company to take on more work? If the answer is unclear, the purchase may be early.
Ask the staff who run the line, not just the equipment seller. A machine that looks fast in a demonstration can still require training, maintenance and changes to the workspace.
2. Will the machine pay for itself, and how quickly?
Suppose the owner works up the following estimates. These are example figures, not a quote or a promise of savings.
| What changes | Estimated amount |
| Machine price | $85,000 |
| Delivery, setup and training | $5,000 |
| Total cash cost to buy and start using it | $90,000 |
| Overtime and temporary packing labour no longer needed, per year | $24,000 |
| Additional profit from orders the business can realistically fill, per year | $20,000 |
| Extra maintenance, power and supplies, per year | ($3,000) |
| Estimated annual cash benefit before tax | $41,000 |
At that level, the rough payback is $90,000 ÷ $41,000 = about 2.2 years. That is a starting point, not a complete return-on-investment calculation. It leaves out financing costs, tax, resale value and the risk of downtime.
The assumptions matter more than the arithmetic. If existing staff are simply moved to other work, that may be useful capacity, but it is not necessarily a $24,000 cash saving. And extra sales only help if the orders are likely to happen and the $20,000 is profit after the additional costs, not just revenue.
3. How do leasing and buying equipment affect cash flow differently?
Imagine the owner also gets a lease quote of $2,200 a month for four years, with $5,000 still needed for setup.
| Option | Cash to get started | Payments over four years |
| Buy for cash | $90,000 including setup | $90,000 total, paid upfront |
| Lease | $5,000 setup, plus monthly payments | $105,600 in payments, plus $5,000 setup |
Buying costs less in total dollars in this example, but it uses $90,000 immediately. Leasing keeps more cash in the business, yet the monthly payments still need to be made during slower months. Before signing, check who owns the machine at the end of the lease, whether there is a buyout price, who pays for repairs and what happens if the equipment is no longer needed.
A full comparison also weighs borrowing costs, tax treatment, resale value and the value of keeping cash available. The lowest monthly payment is not automatically the best deal.
4. Does the purchase still work in a slower year?
Today’s bank balance does not tell you what cash will be available three months from now. Put the purchase or lease into a cash-flow forecast that includes wages, raw materials, rent, loan payments, taxes and the time customers take to pay.
Then reduce the expected new orders. What if they arrive three months later? What if installation takes longer? Can the company still pay its people and suppliers without relying on an expensive line of credit? Those answers may change the timing or how the purchase is funded.
Weighing a purchase like this? Our senior-led team can test the numbers with you. Request a Fit & Scope Call.
5. Does buying equipment before year-end reduce your tax?
In Canada, equipment is generally deducted for tax purposes through capital cost allowance (CCA), which spreads the cost of an asset over time. Some equipment qualifies for a faster deduction.
In September 2026, the federal government also proposed the Productivity Mega Deduction, which would allow an immediate deduction for a wide range of new capital investments, including many types of equipment. It still needs to be finalized, so confirm eligibility and timing with your accountant before relying on it in a purchase decision.
Timing matters. For most equipment, ordering it or paying a deposit before year-end is not enough. The machine generally needs to be ready and available for business use. If a packaging line arrives in December but cannot run until January, the deduction may belong to the following year.
A tax deduction also does not reimburse the price of the machine. It reduces taxable income. The business still needs the cash to pay for the equipment and keep operating.
6. What about PST and other costs in BC?
In British Columbia, provincial sales tax (PST) can apply to equipment purchases and to lease payments. Some production machinery used by qualifying manufacturers may be exempt. Confirm how PST applies to your equipment and business before comparing quotes, because it changes the true cost of both options.
Include insurance, electrical or space changes, and any financing fees in the same comparison, so you are weighing the full cost rather than the sticker price.
7. What should your equipment decision plan include?
Once the numbers support the purchase, a short plan keeps everyone aligned:
- Confirm the business case with the people who will run the machine.
- Get final purchase and lease quotes and compare them on the same basis, including PST and setup costs.
- Decide how to fund it: cash, a loan or a lease, tested against a slower-year forecast.
- Agree on delivery, installation and training dates, noting when the machine will be available for use.
- Have your accountant confirm the tax treatment and the records needed for CCA or lease deductions.
If the machine makes sense for the business, a year-end tax benefit can improve the timing. If it does not, the deduction is a weak reason to spend $90,000. For other items to settle before December 31, see our corporate year-end planning guide.
How Business360.CPA Can Help?
Some lease vs buy decisions are simple. Others affect cash flow, financing, tax timing and the reporting a lender expects, all at once. That is when strategic financial advice is most useful. Our Strategic Finance & Business Advisory work, often described as fractional CFO services, connects the decision with the forecast, the funding and the tax timing.
Our senior-led team works from offices in Vancouver and Burnaby and supports owner-managed businesses across British Columbia. [Business360.CPA to confirm a one-line experience statement, e.g. the types of manufacturers or growth businesses the team supports.] We work alongside your existing bookkeeper, accountant or lender, with clearly allocated responsibilities.
How we work together:
- Fit & Scope Call. A short introductory conversation to understand the decision in front of you and confirm whether we are the right fit.
- Strategic Finance Diagnostic. A paid, focused review of your cash flow, reporting and funding options, tailored to your situation, with a clear comparison and a recommended next step.
- Implementation support. If you would like help carrying out the plan, we agree on responsibilities, timing and fees up front.
Tell us about the equipment you are considering and when you would like it in place. We will explain how we can help and what the next step would involve.
Frequently Asked Questions
Should I buy equipment before year-end to get a tax deduction?
Only if the machine fits your plans and the cash works. In Canada, the deduction generally depends on when the equipment is available for use, not the date on the order form, so delivery and installation timing matter.
Is leasing equipment better than buying when cash is tight?
Leasing can preserve cash at the start, but it usually costs more in total. Compare the full cost of each option and confirm the payments remain affordable if sales slow down.
Can I claim capital cost allowance on leased equipment?
Generally, a business that leases equipment deducts the lease payments rather than claiming CCA, because it does not own the asset. Some leases are treated more like a purchase for tax purposes, depending on their terms, so review the agreement with your accountant.
Does the Productivity Mega Deduction apply to equipment?
It is proposed to allow an immediate deduction for a wide range of new capital investments, which can include equipment. The measure was announced in September 2026 and is not yet final, so check eligibility, timing and the available-for-use rules with your accountant.
What if my business year-end is not December 31?
Use your actual fiscal year-end. The same questions about cash, readiness for use and funding apply to whatever date your year closes.
When does it make sense to involve a fractional CFO in an equipment decision?
When the purchase is large relative to your cash, involves a lender or lease financing, or is part of a wider growth plan. A fractional CFO can build the forecast, compare funding options and prepare the reporting a lender may expect.
Sources and further reading
Rules change. The links below are official starting points; the facts of each business still matter. This article is general information, not advice for your specific situation.
Canada Revenue Agency: when equipment becomes available for use
Department of Finance Canada: proposed Productivity Mega Deduction (September 2026)Province of British Columbia: PST Bulletin 110, Production Machinery and Equipment Exemption